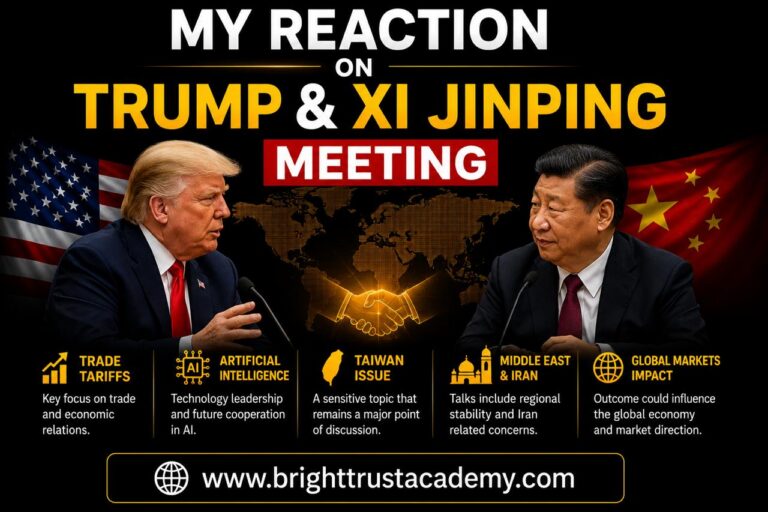
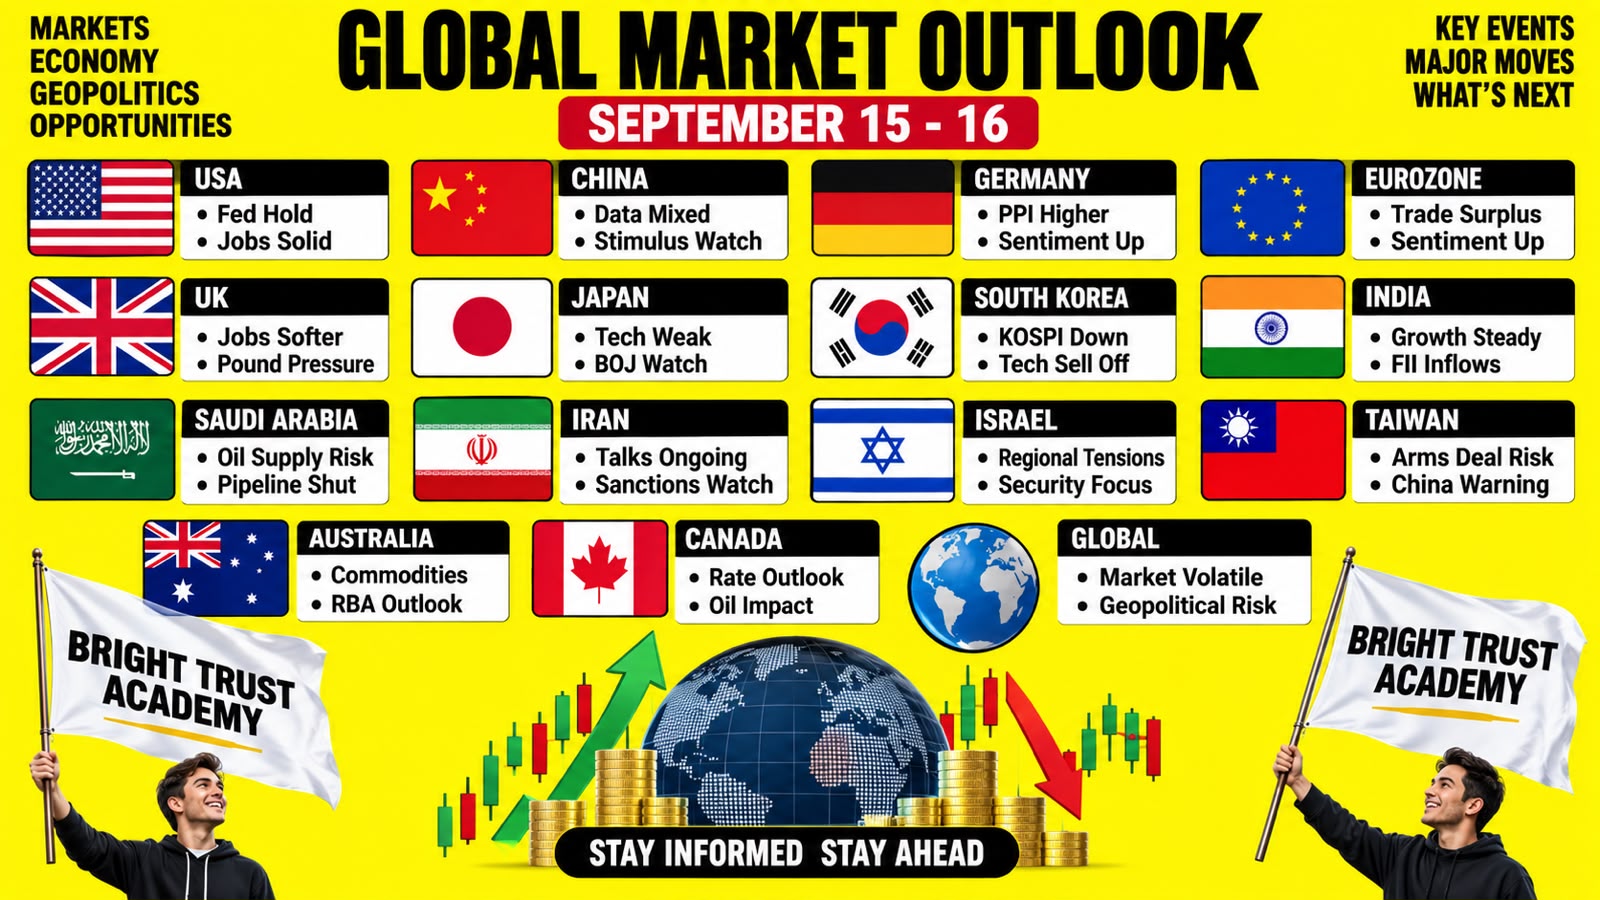
US China And AI: Trump said his relationship with Xi Jinping remains excellent and he is not concerned about a possible cancellation of their meeting. Kyodo reported that China may cancel Xi visit if the US approves a roughly 14 billion dollar Taiwan arms package. The US China trade truce is due to expire on November 10. The leaders are expected to discuss trade. AI development. And the Middle East.
Trump said the US must maintain its AI leadership over China. Anthropic CEO Dario Amodei called for stronger government oversight and independent AI safety verification. OpenAI CEO Sam Altman supported a careful pace for AI development. AI safety concerns triggered major technology market moves. KOSPI fell 3.3 percent. STOXX Europe 600 Technology fell 2.5 percent. ASML fell 6.2 percent. SoftBank fell 10.7 percent.
🛢️ Oil And Middle East: Saudi Arabia fully shut its East West pipeline with capacity of up to 7 million barrels per day after drone attacks near Riyadh and Medina. Strait of Hormuz and Red Sea shipping risks remain elevated because of Houthi attacks and regional tensions. Bahrain refused to attend proposed talks. Oman said Salalah talks were postponed to achieve regional consensus. Iran said the proposed Iran Oman route is not an open corridor and full unblocking depends on a final settlement with Washington. Trump said Iranian authorities are seeking dialogue and suggested the conflict could end after or before the US midterm elections.
China: New home prices were minus 3.2 percent versus minus 3.3 percent previous and minus 3.1 percent forecast. Guangzhou minus 2.2 percent. Shenzhen minus 2.9 percent. Tianjin minus 4.4 percent. Shanghai plus 3.0 percent. Industrial production was 4.5 percent versus 5.3 percent previous and 4.8 percent forecast. Electronics plus 19.1 percent. Shipbuilding plus 13.6 percent. Autos plus 8.7 percent. Mining minus 4.2 percent. Coal minus 10.8 percent. Utilities and energy plus 5.0 percent. Retail data showed auto sales minus 17.0 percent. Furniture minus 8.8 percent. Electronics and communications plus 20.4 percent. Food plus 5.3 percent. Cosmetics plus 6.8 percent.
Germany: PPI was 5.3 percent versus 4.9 percent previous and 6.2 percent forecast. Non ferrous metals plus 27.8 percent. Petroleum products plus 24.1 percent. Chemicals plus 13.1 percent. ICT equipment plus 9.0 percent. Live cattle minus 18.5 percent. Dairy minus 9.4 percent. Meat products minus 6.1 percent. Wholesale prices rose 0.2 percent monthly. ZEW economic sentiment reached 34.2 points versus 26.3 previous and 37.0 forecast. Current conditions improved to minus 61.1 points from minus 77.6 previous versus minus 52.2 forecast.
Eurozone: Goods trade balance was 8.6 billion euros versus minus 9.0 billion previous and 3.7 billion forecast. Exports increased 14.4 percent. Exports to China increased 14.4 percent. Exports to the US increased 10.3 percent. Imports increased 13.1 percent. Eurozone ZEW sentiment rose to 31.4 points from 23.4 previous versus 39.9 forecast. Current situation improved by 16.2 points and inflation expectations declined to 2.4 percent.
UK: Employment change was 83k versus 147k previous and 70k forecast. The report pointed toward softer job creation and a cooling labor market.
US: ADP four week average private payroll gains reached 12k versus 10k previous. The August 22 four week average was reported at 12.5k. Oil data showed refinery runs up 90k barrels per day. Gasoline inventories increased 1.269 million barrels. Distillates increased 2.087 million barrels. Net crude imports increased 1.12 million barrels per day. Markets expected a strong inventory build which could weigh on Brent.
🏦 Federal Reserve: The Fed kept rates unchanged at 3.75 percent versus 4.00 percent forecast. The statement highlighted persistent inflation risks. Readiness to resume tightening. Some officials favoring an immediate hike. And restrictive financial conditions weighing on demand. Markets continued pricing further rate increases which supported the US dollar.
📅 Key Speakers: September 15. Claudia Buch at 11.15. Piero Cipollone at 17.00. Carolyn Wilkins at 18.00. Isabel Schnabel at 20.00. September 16. Boris Vujcic at 15.15.
Main market themes: US China tensions. Taiwan. AI regulation and investment. Oil supply risks. Strait of Hormuz. Middle East diplomacy. China growth. European inflation and sentiment. UK employment. Fed policy. Oil inventories. USD. EUR. GBP. And CNY.